CATEGORY - FEATURES & UPDATES
Payment Gateway vs Payment Processor: What’s the Difference?
Features & updates - 6 Mar, 2024

-
Table of Contents
When a customer makes an online payment, several systems work together to move the transaction from the checkout page to the relevant payment infrastructure and, ultimately, settlement. Two important components of this process are the payment gateway and the payment processor.
Although these terms are often used interchangeably, they perform different roles.
A payment gateway primarily connects the customer-facing checkout or payment interface with the payment infrastructure and securely transmits transaction information. A payment processor works behind the scenes to route transaction information between the merchant, banks, payment networks and other payment participants involved in processing the transaction.
In simple terms, the payment gateway connects the payment experience to the payment ecosystem, while the payment processor facilitates the underlying transaction flow.
Many payment providers combine gateway and processing capabilities into a single payment platform, so businesses may not need to work with separate providers.
What is a Payment Gateway?
A payment gateway is technology that connects a customer's payment experience with the underlying payment infrastructure. It securely captures and transmits the transaction information required to initiate a payment and communicates the transaction result back to the merchant and customer.
For example, when a customer reaches an online checkout and chooses a payment method, the payment gateway facilitates the secure exchange of the information required to initiate the transaction.
Depending on the provider and integration, a payment gateway can support payment methods such as:
-

UPI
-
Credit and debit cards
-
Net banking
-
Wallets
-
Other digital payment methods
The gateway is therefore an important part of the customer-facing payment experience. A well-designed gateway should make it easy for customers to select their preferred payment method, complete authentication where required and understand whether their payment was successful, declined or requires further action.
For businesses, the gateway also provides the connection between the checkout experience and the wider payment infrastructure.
What is a Payment Processor?
A payment processor is back-end infrastructure that facilitates the movement and processing of transaction information between the merchant, banks, payment networks and other relevant payment participants.
When a customer makes a payment, the processor helps route the transaction through the relevant payment infrastructure for authorisation and communicates the response back through the payment flow.
Depending on the payment method and setup, payment processing can involve:
-
Routing transaction information
-
Supporting transaction authorisation
-
Communicating approval or decline responses
-
Supporting clearing and settlement
-
Facilitating transaction information exchange between relevant payment participants
The processor is generally not visible to the customer. Its role is to keep the underlying transaction flow moving between the systems involved in completing a payment.
Difference Between Payment Gateway and Payment Processor
The primary difference is where each component fits into the payment journey.
-
A payment gateway primarily connects the customer's checkout or payment interface with the payment infrastructure and securely transmits transaction information.
-
A payment processor operates behind the scenes to route and process transaction information between the merchant, banks, payment networks and other participants involved in the transaction.
Here's a breakdown to help you understand the difference
A simple way to look at the distinction is:
- A payment gateway: connects the customer-facing payment experience to the payment infrastructure.
- A payment processor: facilitates the underlying transaction flow between the relevant payment participants.
The two are complementary rather than competing technologies. A business accepting online payments generally needs the capabilities provided by both, even when those capabilities come from the same payment provider.
Payment Gateway vs Payment Processor: At a Glance
| Feature | Payment Gateway | Payment Processor |
|---|---|---|
|
Primary role |
Connects the customer-facing payment experience with payment infrastructure |
Facilitates transaction routing and processing between payment participants |
|
Main function |
Securely captures and transmits transaction information |
Routes transaction information and supports authorisation, clearing and settlement |
|
Customer visibility |
More visible to the customer |
Mostly works behind the scenes |
|
Key responsibility |
Secure payment-data transmission and communication of transaction status |
Transaction routing, authorisation support, clearing and settlement |
|
Common use |
Websites, apps, payment pages and other customer-facing payment experiences |
Online and offline transaction processing |
|
Works with |
Checkout systems, processors, banks and other payment infrastructure |
Gateways, banks, card networks and other payment participants |
|
Can one provider offer both? |
Yes |
Yes |
The exact responsibilities can vary depending on the payment method, provider and payment setup. In many modern payment platforms, gateway and processing capabilities are combined.
How Do Payment Gateway and Payment Processor Work Together?
A payment gateway and payment processor work together as parts of the same payment journey.
Consider a customer purchasing a product online.
-
Customer Initiates the Payment: The customer selects a payment method such as UPI, card or net banking and initiates the transaction on the merchant's website, app or payment page.
-
Payment Gateway Connects the Checkout to the Payment Infrastructure: The gateway securely captures and transmits the relevant transaction information to the payment infrastructure.
-
Payment Processor Routes the Transaction: The processor facilitates the movement of transaction information through the relevant payment infrastructure and payment participants.
-
Transaction Is Authorised or Declined: The relevant financial institution or payment participant evaluates the transaction according to applicable authentication, account, balance, credit and risk controls and returns an approval or decline response.
-
The Response Travels Back: The transaction result travels back through the payment infrastructure to the merchant's payment system.
-
Customer and Merchant Receive the Status: The payment interface communicates whether the transaction was successful, declined, pending or requires further action.
-
Successful Transactions Proceed to Settlement: For successful transactions, funds subsequently move through the applicable clearing and settlement process before reaching the merchant according to the payment method, provider and agreed settlement cycle.
A simplified payment flow can be represented as:
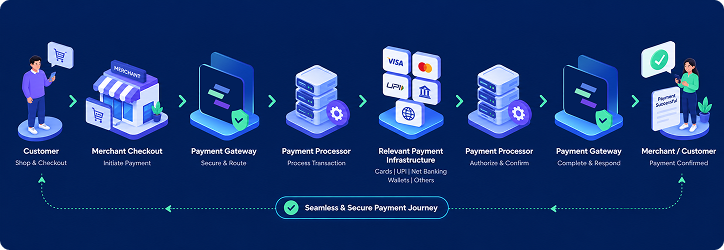
The exact technical flow can vary depending on the payment method and infrastructure involved. Card payments and UPI payments, for example, operate through different payment ecosystems.
How Does a Payment Gateway Work?
A payment gateway plays an important role in connecting the customer's payment experience with the underlying payment infrastructure.
A typical online payment journey involves the following steps.
-
Payment Method Selection: The customer chooses an available payment method such as UPI, card, net banking or another supported option.
-
Secure Payment Data Capture: The gateway or relevant payment interface captures the information required to initiate the transaction using appropriate security measures.
-
Secure Payment Data Transmission: The relevant transaction information is securely transmitted to the payment infrastructure for processing.
-
Payment Authorisation: The payment request is routed through the applicable payment infrastructure for authentication and authorisation.
-
Transaction Response: The approval, decline or other transaction response is returned through the payment infrastructure.
-
Transaction Confirmation: The payment interface communicates the transaction status to the customer and merchant.
-
Settlement: For successful transactions, the funds proceed through the applicable clearing and settlement process.
In short, a payment gateway can be valuable if your business involves any online transaction. It streamlines the payment process for your customers, improves security, and opens doors to new revenue opportunities.
How Does a Payment Processor Work?
Payment processing involves several systems and participants working together to authorise and complete a transaction.
-
Transaction Routing: The processor facilitates the routing of transaction information through the relevant payment infrastructure.
-
Authorization: The transaction is sent through the applicable payment network or payment infrastructure to the relevant bank or payment participant for authorisation.
-
Approval or Decline: The relevant participant evaluates the transaction and returns an approval, decline or other applicable response.
-
Response Handling: The transaction response is communicated back through the payment infrastructure to the merchant's payment system.
-
Clearing: For successful transactions, transaction information is processed through the applicable clearing process between participating institutions.
-
Settlement: Funds subsequently move through the applicable settlement process according to the payment method, provider and agreed settlement cycle. Settlement timelines are not the same for every transaction. They can vary based on the payment method, transaction type, provider and merchant agreement.
Payment Gateway vs Payment Processor vs Payment Aggregator
Businesses in India may also come across the term payment aggregator while evaluating payment solutions.
-
A payment gateway generally refers to technology that connects the customer-facing payment experience with payment infrastructure and securely transmits transaction information.
-
A payment processor refers to infrastructure that facilitates transaction routing and processing between relevant payment participants.
-
A payment aggregator is a broader payment service model that enables merchants to accept payments through multiple payment methods and manages relevant payment acceptance and settlement processes.
The terminology and responsibilities can vary between providers and payment setups. Businesses should therefore evaluate the actual capabilities and services offered rather than choosing a provider based only on whether it describes itself as a gateway, processor or aggregator.
| Payment Term | What It Generally Refers To |
|---|---|
|
Payment Gateway |
Technology connecting the payment interface with payment infrastructure |
|
Payment Processor |
Infrastructure facilitating transaction routing and processing |
|
Payment Aggregator |
A payment service model that enables merchants to accept payments through multiple payment methods and manages relevant payment acceptance and settlement processes. |
|
Payment Service Provider |
A broader provider that may combine multiple payment services and capabilities |
Do Businesses Need Both a Payment Gateway and Payment Processor?
Most online payment setups require both gateway and processing capabilities. However, businesses do not necessarily need to work with separate providers.
Many payment platforms combine gateway, processing and other payment capabilities into a single integrated solution.
This can simplify implementation and payment operations because a business may be able to manage payment acceptance, transaction visibility, refunds, settlements and reconciliation through one platform or integration.
The important question is therefore not simply:
Do I need a payment gateway or a payment processor?
Instead, businesses should ask:
Does my payment partner provide the payment infrastructure and operational capabilities I need from checkout to settlement?
Payment Gateway vs Payment Processor Fees
The cost of accepting digital payments can depend on several factors, and there is no single standard fee that applies to every payment gateway or processor.
Pricing may vary based on:
-
Payment method
-
Transaction type
-
Business model
-
Transaction volume
-
Domestic or international payments
-
Provider
-
Commercial agreement
-
Additional payment services or platform capabilities
Depending on the provider, businesses may encounter transaction-based fees, percentage-based charges, fixed fees, setup or onboarding charges, platform fees or other applicable charges.
When comparing payment solutions, businesses should look beyond the headline transaction fee and consider the overall cost of payment acceptance.
For example, a solution with a lower transaction fee may not necessarily be more cost-effective if it lacks the integrations, reporting, reconciliation, refund management or operational capabilities a business needs.
Which Payment Solution Does Your Business Need?
There is no single payment setup that works for every business. The right solution depends on the business model, payment channels, transaction volumes, customer preferences and operational requirements.
-
E-commerce Businesses: Online stores typically need a payment solution that supports multiple payment methods, provides a smooth checkout experience, integrates with their commerce platform and offers visibility into successful, failed, pending and refunded transactions.
-
SaaS and Subscription Businesses: Subscription businesses may need capabilities for recurring collections, payment status tracking, APIs, refunds, transaction reporting and reconciliation.
-
Education Businesses and Institutions: Schools, colleges, universities and education platforms may require online payment acceptance along with receipts, fee tracking, reminders, refunds, reconciliation and collection reporting.
-
Marketplaces and Platforms: Businesses managing multiple sellers, vendors or service providers may require capabilities such as sub-merchant management, onboarding, payment splitting and settlement workflows.
-
Offline and Online Businesses: Businesses operating across physical and digital channels may benefit from payment infrastructure that supports online payments, POS transactions and unified transaction visibility.
-
Growing Businesses: As transaction volumes and operational complexity increase, businesses may need stronger capabilities around payment reliability, reporting, refunds, reconciliation, settlements, integrations and support.
What Should Businesses Look for in a Payment Solution?
The gateway-versus-processor distinction is useful for understanding how payments work, but it should not be the only factor businesses consider when selecting a payment partner.
-
Multiple Payment Methods: Customers have different payment preferences. Businesses should evaluate whether the provider supports the payment methods relevant to their customers and business model.
-
Checkout Experience: The payment experience should be clear, easy to navigate and suitable for the devices customers use. Unnecessary friction at checkout can affect payment completion and customer experience.
-
Easy Integration: Businesses should consider APIs, documentation, plugins and integrations that fit their existing technology stack.
-
Transaction Reliability: Businesses should have visibility into successful, failed, declined and pending transactions and understand how the provider handles different transaction scenarios.
-
Security and Compliance: Payment infrastructure should use appropriate security controls and comply with applicable requirements to support secure payment acceptance.
-
Refund Management: Businesses should be able to initiate, track and manage refunds efficiently while maintaining a clear transaction history.
-
Reconciliation: As transaction volumes grow, manually matching payments with orders, invoices and settlements can become difficult. Automated reconciliation can reduce manual work and improve financial visibility.
-
Settlement Visibility: Businesses should have clear information about settlements and relevant transaction-level details.
-
Reporting: Payment reporting can help businesses monitor transaction performance, settlements, refunds and other payment activity.
-
Scalability: Payment infrastructure should be able to support the business as transaction volumes, payment methods, customers and sales channels grow.
-
Customer Support: Businesses should also consider the availability and quality of technical and operational support, particularly when payment issues can directly affect revenue and customer experience.
What Matters More Than Gateway vs Processor?
For most businesses, understanding the difference between a gateway and processor is only the starting point.
The more important question is whether the overall payment infrastructure can support the complete payment lifecycle.
That includes:
-
Payment acceptance - Can customers pay using the methods they prefer?
-
Checkout - Is the payment experience simple and reliable?
-
Processing - Can transactions be routed and processed efficiently?
-
Security - Are appropriate controls in place to protect payment information?
-
Transaction Visibility - Can the business understand successful, failed and pending transactions?
-
Refunds - Can refunds be initiated and tracked efficiently?
-
Reconciliation - Can payments, orders and settlements be matched accurately?
-
Settlement - Can the business clearly track when and how funds are settled?
-
Integration - Can payment data work with the business's existing systems?
-
Scalability - Can the payment infrastructure support future growth?
Looking at the complete payment lifecycle gives businesses a more practical basis for choosing a payment partner than comparing the labels "gateway" and "processor" alone.
Choosing a Payment Partner in India
For businesses in India, payment infrastructure needs to support the payment methods, customer journeys and operational requirements relevant to the Indian market.
Businesses may need support for UPI, cards, net banking and other payment methods, along with APIs, checkout experiences, transaction visibility, refunds, reconciliation and settlement management.
Easebuzz provides payment infrastructure and solutions that bring together payment acceptance and payment operations across different business requirements.
The right payment partner ultimately depends on the business model, payment methods, transaction volumes, integrations, operational requirements and the level of payment management the business needs.
Payment Gateway vs Payment Processor: Key Takeaways
A payment gateway and payment processor perform different but connected roles in the payment ecosystem.
-
A payment gateway primarily connects the customer-facing checkout or payment interface with payment infrastructure and securely transmits transaction information.
-
A payment processor works behind the scenes to facilitate transaction routing and processing between the merchant, banks, payment networks and other payment participants.
-
Gateway and processing capabilities are complementary and are often provided together by a single payment platform.
-
The exact technical flow can vary depending on the payment method, provider and payment infrastructure involved.
-
Payment gateway and processor fees can vary based on payment method, transaction type, volume, provider and commercial terms.
-
Businesses should evaluate the complete payment lifecycle, including checkout, payment methods, processing, security, refunds, reconciliation, settlement, reporting, integrations and support.
-
A payment aggregator is a broader payment service model and should not automatically be treated as synonymous with a payment gateway or processor.
In simple terms, the payment gateway connects the checkout to the payment ecosystem, while the payment processor facilitates the underlying transaction flow.
FAQs
What is the difference between a payment gateway and a payment processor?
A payment gateway primarily connects the customer-facing checkout or payment interface with payment infrastructure and securely transmits transaction information. A payment processor works behind the scenes to route and process transaction information between the merchant, banks, payment networks and other payment participants.
Is a payment gateway the same as a payment processor?
No. A payment gateway and payment processor perform different functions. The gateway primarily connects the payment experience with the payment infrastructure, while the processor facilitates the underlying transaction flow.
Do I need both a payment gateway and a payment processor?
Most online payment setups require both gateway and processing capabilities. However, businesses do not necessarily need separate providers because many payment platforms combine these capabilities.
Can a payment gateway and payment processor be the same company?
Yes. Many payment providers offer gateway and processing capabilities together as part of an integrated payment solution.
How do payment gateways and processors work together?
The payment gateway connects the customer's payment experience with the payment infrastructure, while the processor facilitates the underlying transaction flow. Together, they help move a payment request from checkout through authorisation and toward completion and settlement.
What is the difference between a payment gateway and a payment aggregator?
A payment gateway is primarily technology that connects a payment interface with payment infrastructure and securely transmits transaction information. A payment aggregator is a broader payment service model that enables merchants to accept payments through multiple payment methods and manages relevant payment acceptance and settlement processes.
What payment methods can a payment gateway support?
Payment methods depend on the provider and integration. Common options include UPI, credit and debit cards, net banking and wallets. Businesses should check which payment methods are supported for their specific use case.
How much does a payment gateway cost?
Payment gateway costs vary by provider, payment method, transaction type, transaction volume and commercial agreement. Businesses should compare the overall cost of payment acceptance rather than looking only at the headline transaction fee.
Does a payment gateway handle settlement?
Settlement depends on the payment setup and provider. A payment gateway primarily connects the payment interface with the payment infrastructure, while successful transactions subsequently proceed through the applicable clearing and settlement process.
Is a payment gateway needed for UPI payments?
A business needs appropriate payment infrastructure to accept UPI payments online. Depending on the provider and setup, gateway, processing and other payment capabilities may be combined within a single payment solution.
Can a payment gateway be used for school and college fee payments?
Yes. A payment gateway can enable online fee payments through a website, app or payment page. Education institutions may also need additional capabilities such as fee tracking, receipts, reminders, refunds, reconciliation and collection reporting.
What should businesses check before choosing a payment gateway?
Businesses should consider supported payment methods, checkout experience, integration options, transaction reliability, security and compliance, refunds, reconciliation, settlement visibility, reporting, scalability, pricing and customer support.
Is Easebuzz a payment gateway or payment processor?
Easebuzz provides payment infrastructure and solutions that enable businesses to accept and manage digital payments. Depending on the product and business requirement, its solutions bring together capabilities across payment acceptance and payment operations.
Share:


